
Taxing Connectivity: How Taxes and Tariffs Deepen Pakistan’s Digital Divide
Executive Summary
Digital connectivity is no longer a discretionary consumer good; it is a core economic infrastructure underpinning productivity, innovation, employment, and social inclusion. In Pakistan, however, the promise of digital transformation is constrained by a fiscal and regulatory framework that prioritizes revenue and localization over access and competitiveness. High and layered taxation and customs tariffs on mobile handsets and broadband services have deepened Pakistan’s digital divide, escalating the persistent usage gap despite widespread network coverage.
This report examines how Pakistan’s tax regime- spanning mobile device import duties, the Device Identification, Registration and Blocking System (DIRBS), telecom service taxation, and the Mobile Device Manufacturing Policy (MDMP) 2020 has increased the cost of digital access and undermined national digital objectives. The policy has successfully created over 60,000 jobs since 2021, with local mobile assembly plants in Pakistan. Using administrative data, international comparisons, and household-level evidence from the Household Integrated Economic Survey HIES 2024-25, the analysis shows that smartphone affordability is a binding constraint on digital inclusion.
This paper finds that while MDMP has succeeded in shifting imports from finished phones to CKD/SKD kits, it has failed to generate meaningful localization, noticeable price reductions, or foreign exchange savings. While local assembly has increased, domestic value addition remains minimal with most of the mobile phone components still being imported. Instead, high effective tax rates-exceeding 50% on higher-end devices have fuelled grey market activity, distorted consumer choice, and weakened revenue efficiency.
In addition to raising the cost of smartphones, Pakistan’s taxation regime has created broader structural barriers to economic modernization and digital participation. Affordable connectivity should be viewed as a national development priority rather than a narrow fiscal instrument. Smartphones and broadband services are no longer optional consumer products. They are gateways to education, employment, innovation, entrepreneurship, and participation in the digital economy. By lowering barriers to digital access and aligning industrial policy with inclusion and competitiveness, Pakistan can accelerate economic modernization, strengthen human capital, and unlock the full potential of its young and increasingly connected population.
The report concludes that aligning fiscal policy with digital inclusion goals requires rationalizing device and service taxes, removing abrupt tax cliffs, and replacing unconditional protection with performance-based industrial incentives. It argues for a strategic policy shift that recognizes digital connectivity as essential national infrastructure rather than a revenue tool because affordable digital access is fundamental to Pakistan’s economic competitiveness and social inclusion.
1. Introduction
Digital Inclusion as a Driver of Productivity and Innovation
In modern economies, digital inclusion has become a necessity rather than a luxury. It is a fundamental driver of economic development, social progress, and competitiveness across countries. Countries that control data and platform infrastructure capture the largest share of digital value.2 Thus, digital inclusion, which ensures that all individuals and communities have access to affordable and effective information, has become a prerequisite for active participation in the global economy.
The mechanism by which economies transform through digital inclusion is well-documented. Access to digital tools enhances the productivity of Small and Medium Enterprises (SMEs) and enables them to enter new markets through e-commerce, streamlines supply chains, and effectively reduces costs by enabling a remote working environment. This is particularly crucial for low- and middle-income countries, which constantly face challenges such as high energy costs, inadequate human capital, and infrastructure. Expanding mobile internet access in low- and middle-income countries is critical for job creation and digital inclusion.3 The digital inclusion thus helps them translate their potential into meaningful economic returns. Similarly, digital inclusion also drives innovation by providing affordable access to digital devices and the internet to fuel a vibrant digital economy. This affordable access can help freelancers participate in the global economy, help small businesses generate income and jobs, and foster an environment where local digital solutions are developed.
Empirical evidence also suggests that digital connectivity is a transformative force driving economic growth and employment, where the mobile industry contributed to 6% of global GDP in 2024 and has the potential to go up to 8% in 2030.4 Similarly, digital connectivity also increases the employment rate and income of individuals compared to those not connected to the internet.
Background and Research Objectives
The government has acknowledged the importance of digital connectivity and taken initiatives such as Digital Pakistan Vision 2047, Digital Nation Pakistan Act, 2025,5 Uraan Pakistan, and policies aligned with digital inclusion. However, this recognition is incomplete or ineffective if the country’s fiscal policies are not aligned with its digital policies. Mobile devices in Pakistan continue to face heavy tax and tariffs, including customs duties, additional customs duties, regulatory duties, withholding tax, and elevated sales tax. On the services side, layered taxation in the form of Advance Income Tax, Federal Excise duties, or provincial sales tax on services continues to increase the cost of mobile broadband. Thus, in practice, the current fiscal framework runs counter to the government’s stated objectives and goals of expanding digital access and narrowing the usage gap.
Pakistan has one of the highest sector-specific taxation rates on telecom taxes in the region. Taken together, all forms of telecom taxation can account for up to 34.5% of the cost of internet access for end users,6 making the internet costly for consumers and making it difficult for low- to middle-income consumers to maintain regular digital access.
The study analyses the effectiveness of the Mobile Device Manufacturing Policy (MDPM) 2020, which was introduced the following year after the rollout of taxes on imported mobile phones. The MDMP aimed to encourage local manufacturing of mobile phones, deepen value addition, create jobs, and increase exports of “Made in Pakistan” Mobile Phones. However, even after 5 years of the policy, none of the objectives have been fully achieved, and localisation of mobile phones has been reduced to local assembly rather than actual manufacturing. Moreover, the combination of MDMP and DIRBS has created a market structure in which consumers face higher prices, especially for imported mobile phones, and even for locally produced mobile phones. The study thus evaluates the effectiveness of the MDMP and the possible affordability constraints it has created for the consumers. This should be useful, timely and relevant as the government is considering a new “Mobile and Electronic Devices Manufacturing Policy (2026-33)”.
Against this backdrop, the study aims to address three core questions.
- How do taxes on mobile phones, across both CBU and CKD/SKD imports, affect the retail cost and affordability of devices?
- How effective has the Mobile Device Manufacturing Policy (MDMP) 2020 been in achieving its objectives?
- How taxation of telecom services, specifically Advance Income Tax, Federal Excise Tax, or Provincial Sales Tax, affects the cost of mobile broadband?
These research questions anchor the study’s overarching objective: to assess the extent to which Pakistan’s tax and regulatory framework create barriers to affordable connectivity and to identify policy reforms that can lower costs, enhance adoption, and align fiscal structures with national digital goals.
2. Current Landscape of Digital Connectivity in Pakistan
Pakistan’s digital connectivity has seen considerable progress in recent years. This is evident from the fact that Pakistan has witnessed rapid expansion in mobile broadband networks over the last decade, where now 81% of the population resides in areas covered by 3G/4G, compared to only 15% in 2010.7 Similarly, smartphone uptake has also seen an increase in recent years. Owing to this growth in internet access and mobile phone ownership, Pakistan’s IT sector has emerged as a bright spot in exports. The sector registered significant growth in recent years. In FY 2024-25, export remittances from IT and IT-enabled services reached $3.81 billion, the highest ever for the country.8 Similarly, IT exports reached $2.61 billion during July–January FY2025–26, showing a 19% Year on Year growth.9 Furthermore, Pakistan has an estimated 111 million internet users, representing around 47% of the population. This is a noticeable 27% increase from last year. Similarly, broadband penetration, which includes both mobile and fixed, stands at 57%, and the country hosts around 195 million subscribers, with a teledensity of around 80.5%.
Figure 1: Cellular Penetration in Pakistan
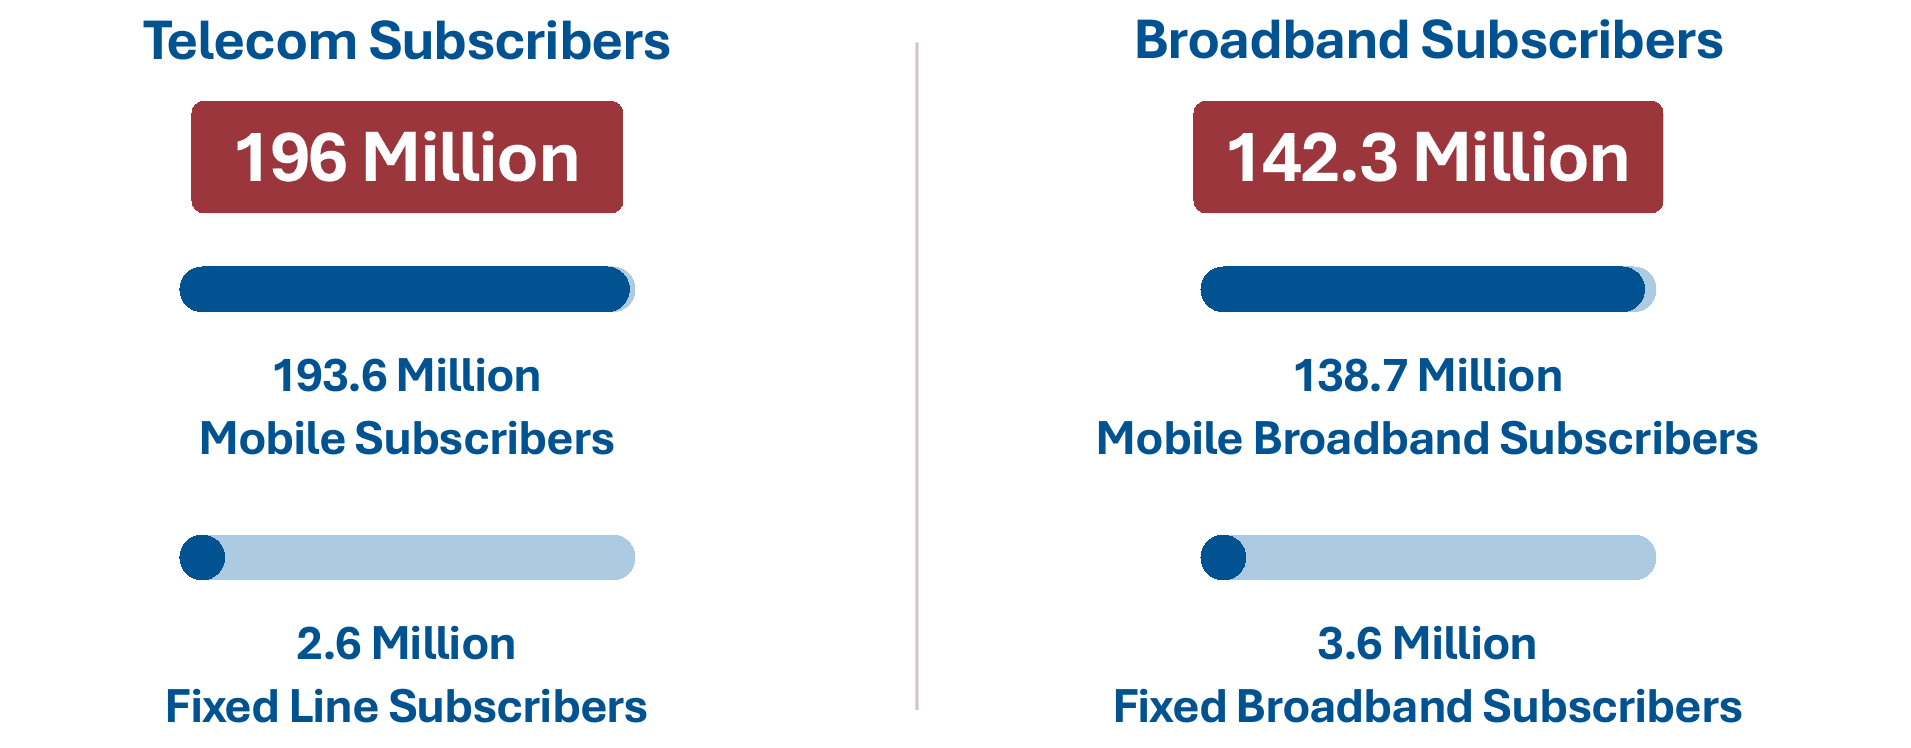
Source: Pakistan Telecommunication Authority Annual Report 2023-24
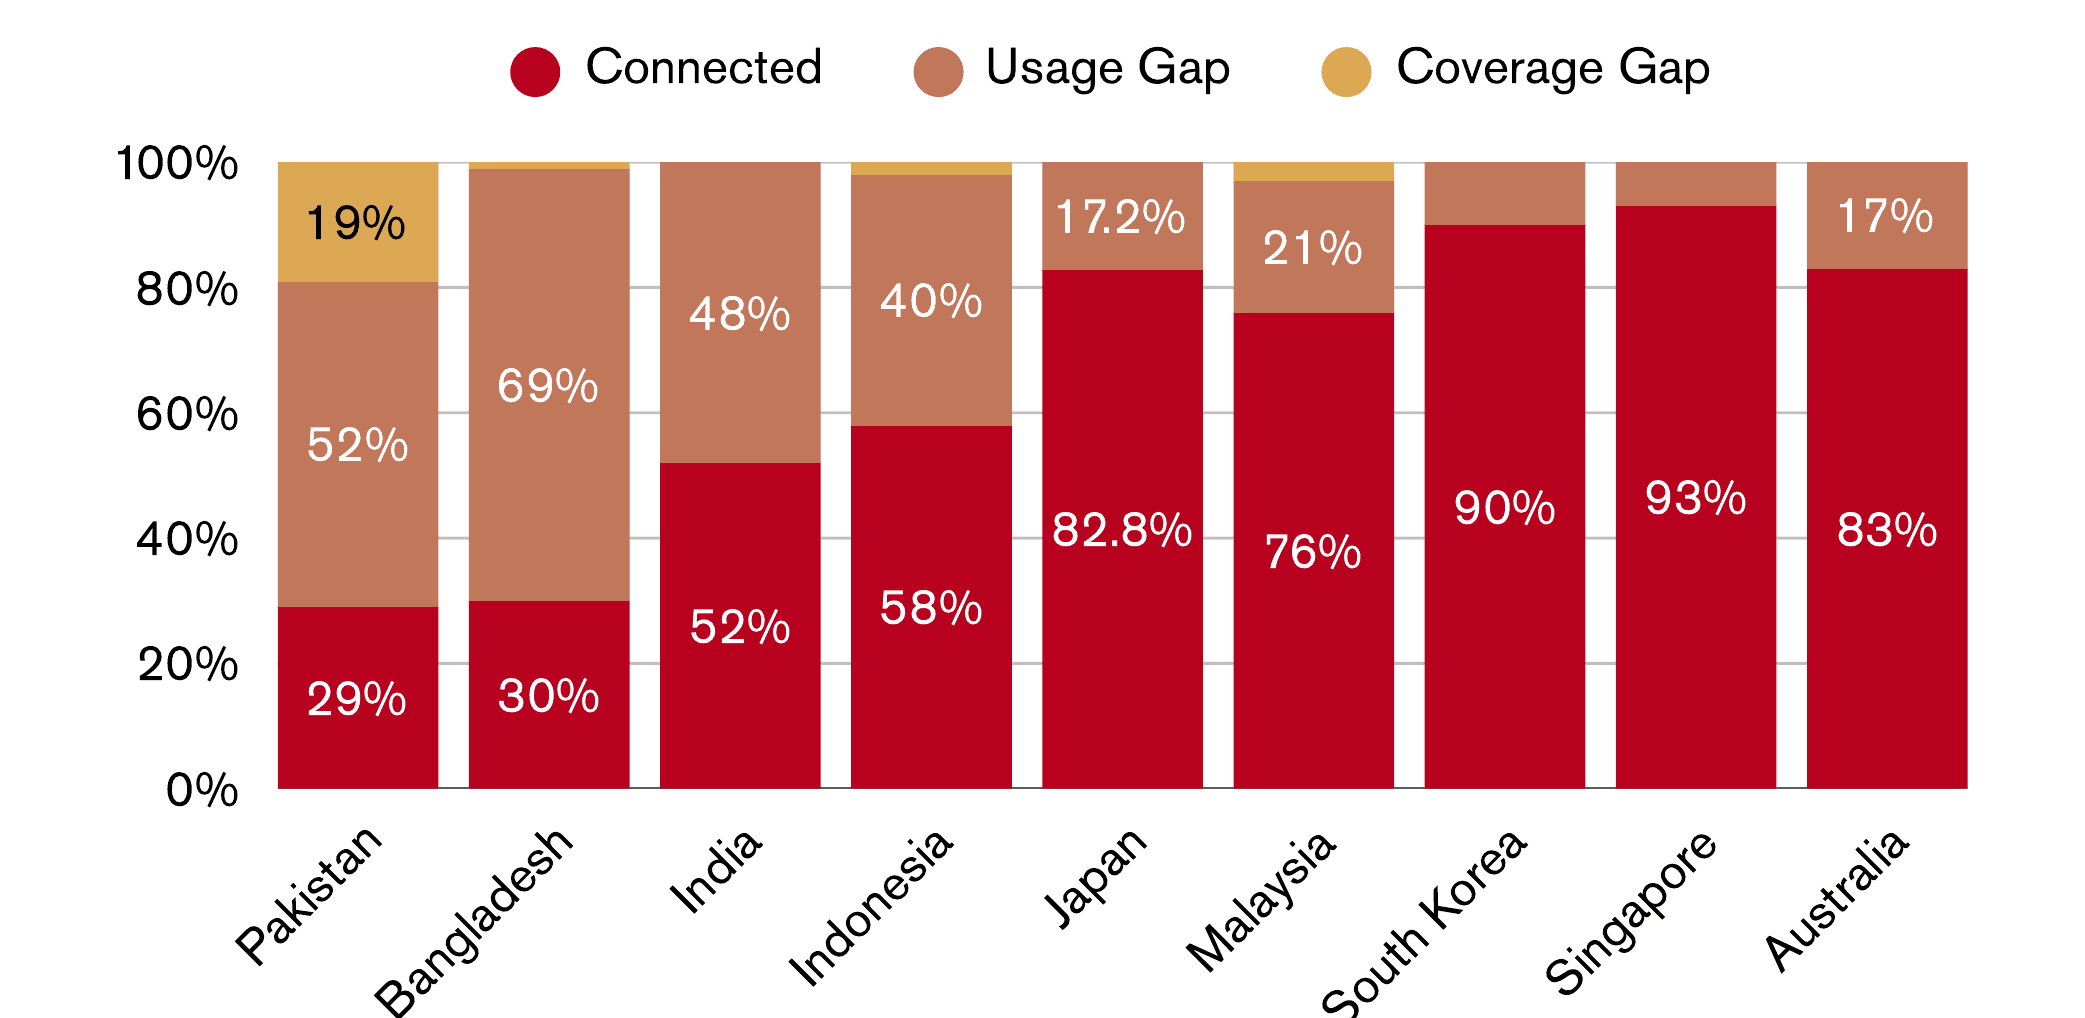
Despite the progress achieved in digital connectivity, certain challenges exist that could potentially hamper the growth of the digital economy. One of the challenges is the deep divide that persists between infrastructure availability and usage. Pakistan’s 81% of the area is covered by 3G/4G connectivity; however, only 29% of the population uses the internet, creating a usage gap of 52%.10 This is one of the major usage gaps in the Asia-Pacific Markets, as shown in the figure below. This indicates that Pakistan’s digital inclusion challenge is driven more by a usage gap than a coverage gap. While 19% of people without internet access present a worrisome picture, the more concerning point is that even among the 52% with access, they do not use it. This highlights that Pakistan’s digital divide is rooted in affordability barriers, high taxation on devices and data, lack of awareness, and low digital literacy, rather than in infrastructure availability alone.
Figure 2: Usage gap across Asia-Pacific Countries
Source: GSMA 2024
Comparing Pakistan’s digital performance with peer countries, Bangladesh (with a 69% usage gap) faces a similar crisis. At the same time, India and Indonesia perform slightly better than Pakistan and Bangladesh, indicating that improving smartphone and internet affordability can directly reduce digital exclusion. Interestingly, like Pakistan, Bangladesh also introduced its Mobile Phone Manufacturing Policy in 2017, under which imported mobile phones faced higher customs duties than mobile phone kits, which were imported to boost local mobile phone manufacturing. However, as in Pakistan, localisation has remained limited to assembly rather than actual manufacturing in Bangladesh as well. In terms of pricing, price comparison between locally assembled and imported mobile phones is not uniform; while imported CBU devices often face higher tariffs and retail prices, locally assembled phones benefit from tax incentives that can make them more affordable in comparable segments. In contrast, digitally advanced countries have higher connectivity and a lower usage gap, suggesting that the affordability of digital devices and the internet can not only increase digital readiness but also have a spillover effect on the overall economy.
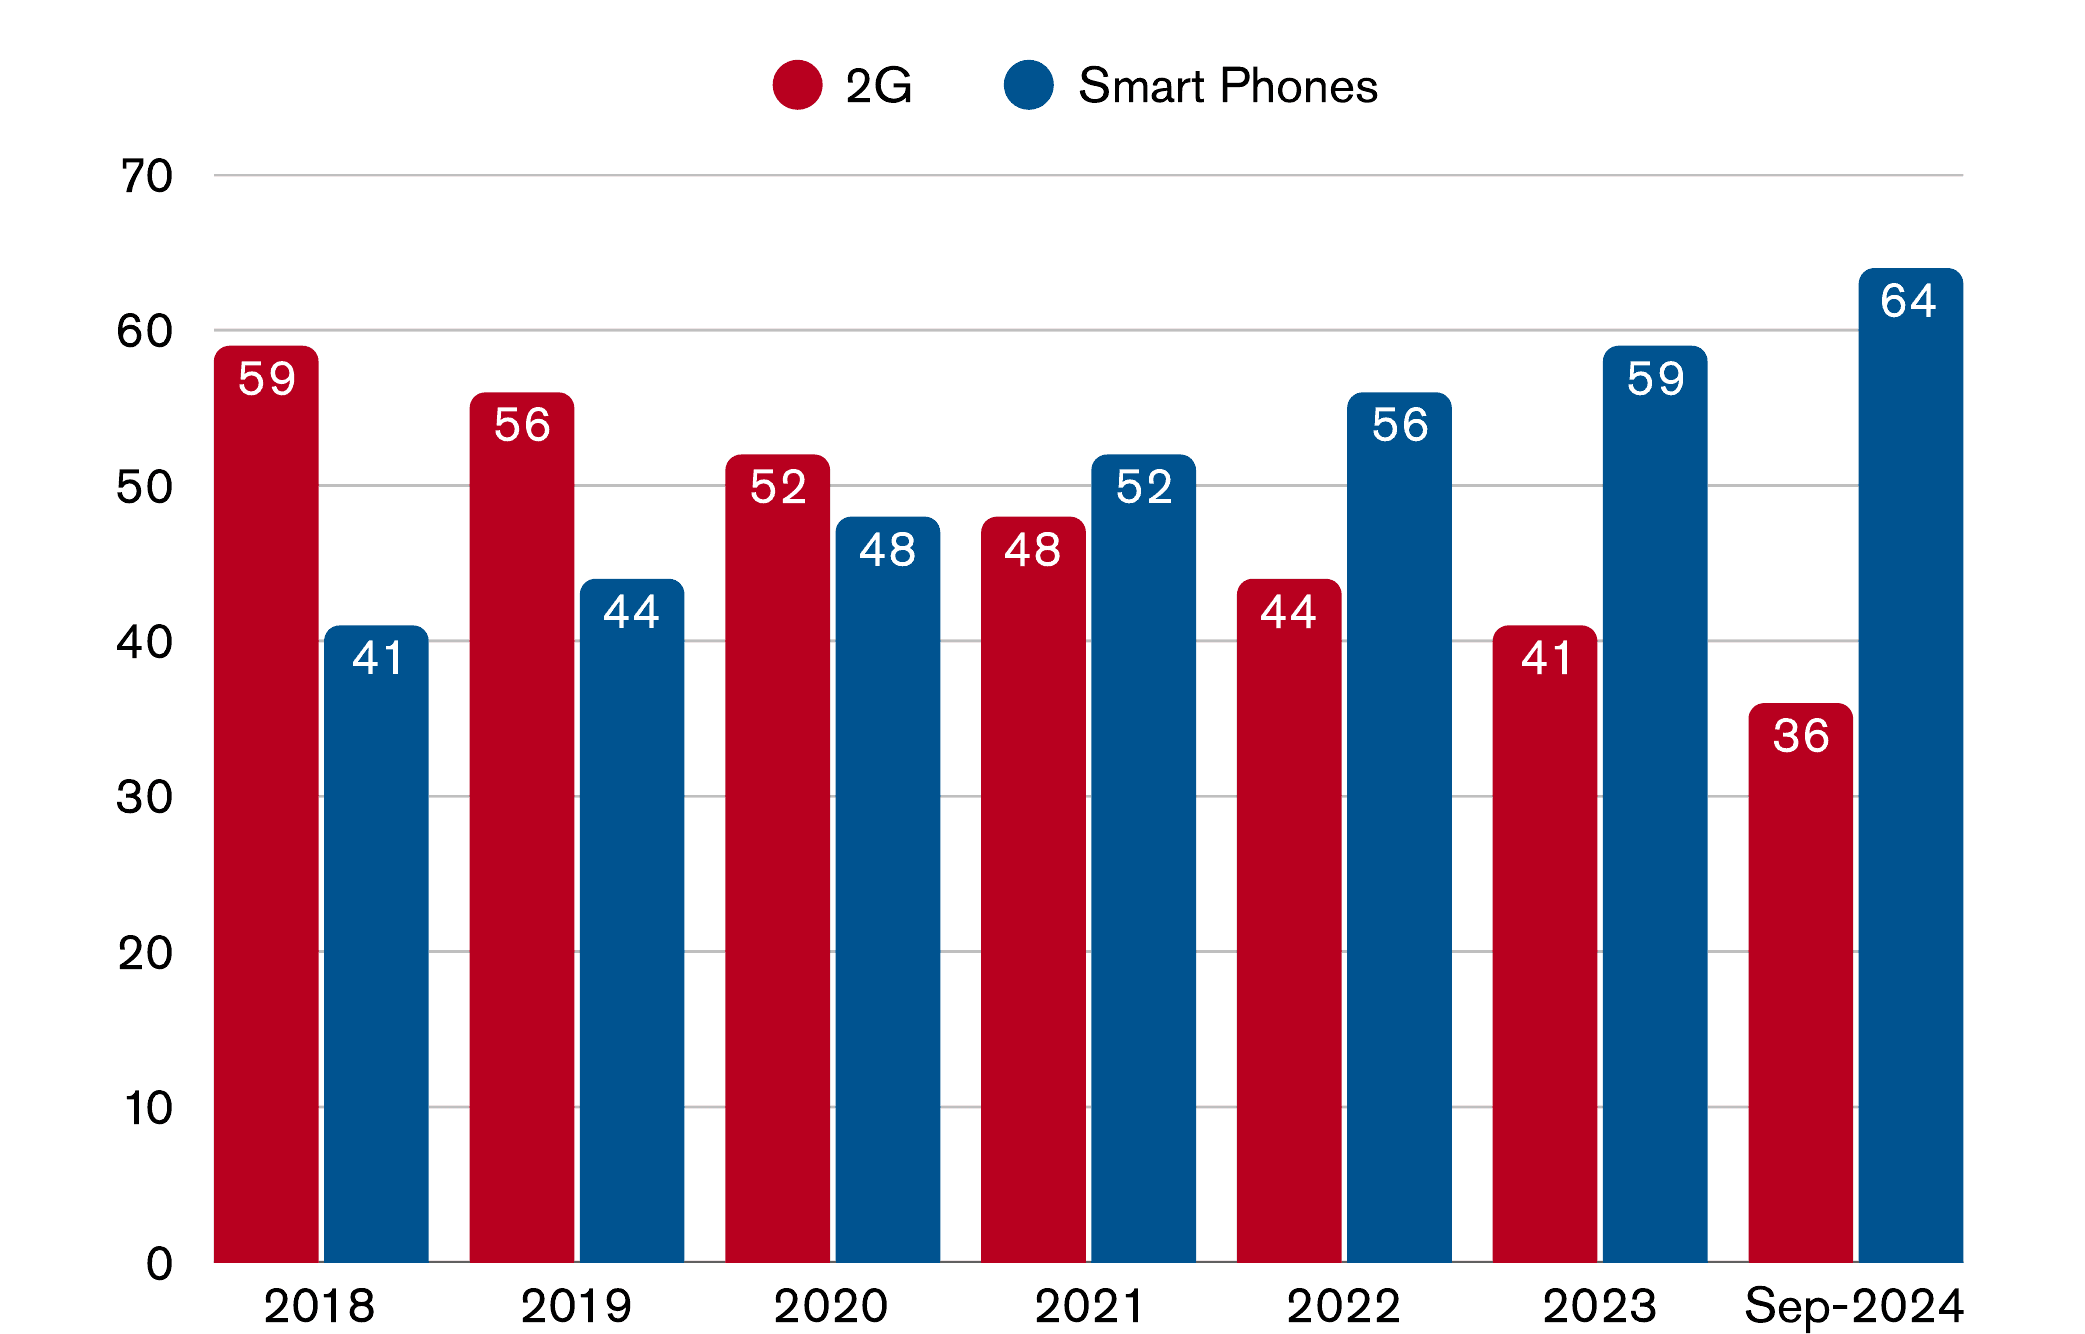
Smartphone ownership reflects similar disparities. Smartphone adoption penetration stands at 63-68% in 2023-24, with modest growth as local assembly increased. Yet low-income households continue to rely on basic or second-hand devices, and the cost of upgrading to entry-level smartphones remains prohibitive. This is particularly due to tax-induced inflation in the devices.
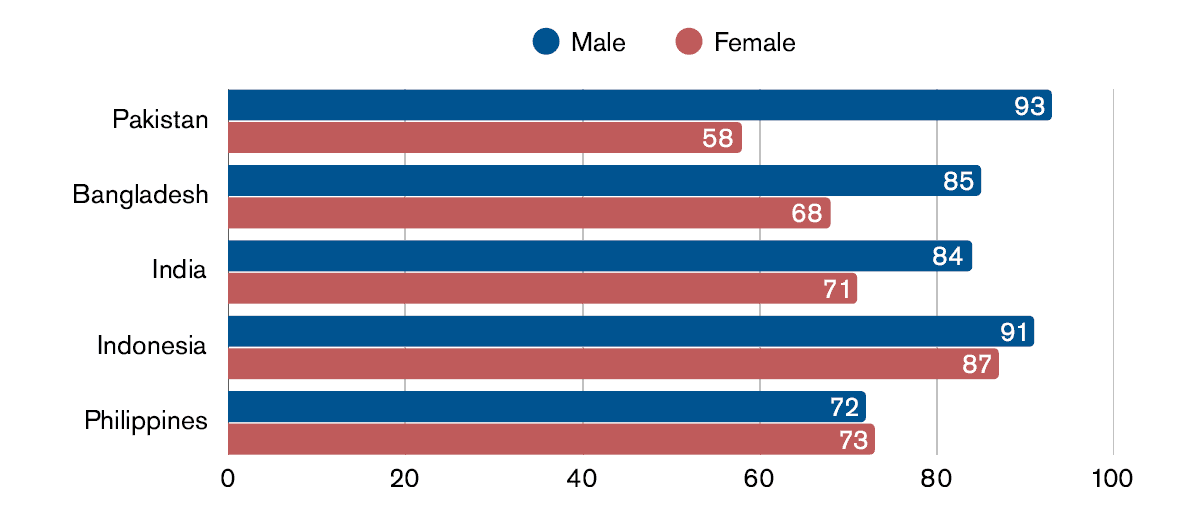
Digital inclusion challenges remain most acute for women and the rural poor. Pakistan’s gender gap in mobile ownership and mobile internet usage is one of the highest in the region. While some consider cultural barriers as the primary reason, factors such as affordability and digital literacy cannot be ignored. Despite making up almost half of the population, most of the women in Pakistan don’t have access to mobile phones, let alone the internet.
Figure 3: Mobile Devices on Pakistan Network
Source: Pakistan Telecommunication Authority
Figure 4: Gender disparity in Mobile Phone Ownership across the region
Source: GSMA, The Mobile Gender Report 2025
The following data suggests that Pakistan has one of the most significant gender gaps in mobile phone ownership among its peers. The same gap is significantly lower for its neighbouring countries, which have a similar culture.
Structure of Pakistan’s Digital Ecosystem
A combination of industrial strategy, regulatory interventions, and policy fragmentations shapes Pakistan’s digital ecosystem. The mobile market has transformed due to MDMP 2020, which was initially launched to promote the local manufacturing of mobile phones. By 2024, 95% of local demand was met by locally produced mobile phones. Annual local manufacturing reached a notable number of 30.21 million units in 2025. However, this expansion in local assembly has not translated into meaningful localisation of the mobile phones, nor into a significant price reduction for the consumers. This is because most local production has remained low-value CKD/SKD assembly with limited localization of core components such as batteries, motherboards, etc. Pakistan’s value chain heavily relies on imported parts, so taxes on kits and components and 18% Sales Tax on finished sets still burden consumers. Despite the presence of more than 30 local assembles the competitive landscape is shaped by significant tariff protection. As a result, competition is largely confined within a protected domestic segment, reducing incentives for innovativeness, efficiency and price competitiveness, ultimately leading to higher prices for consumers.
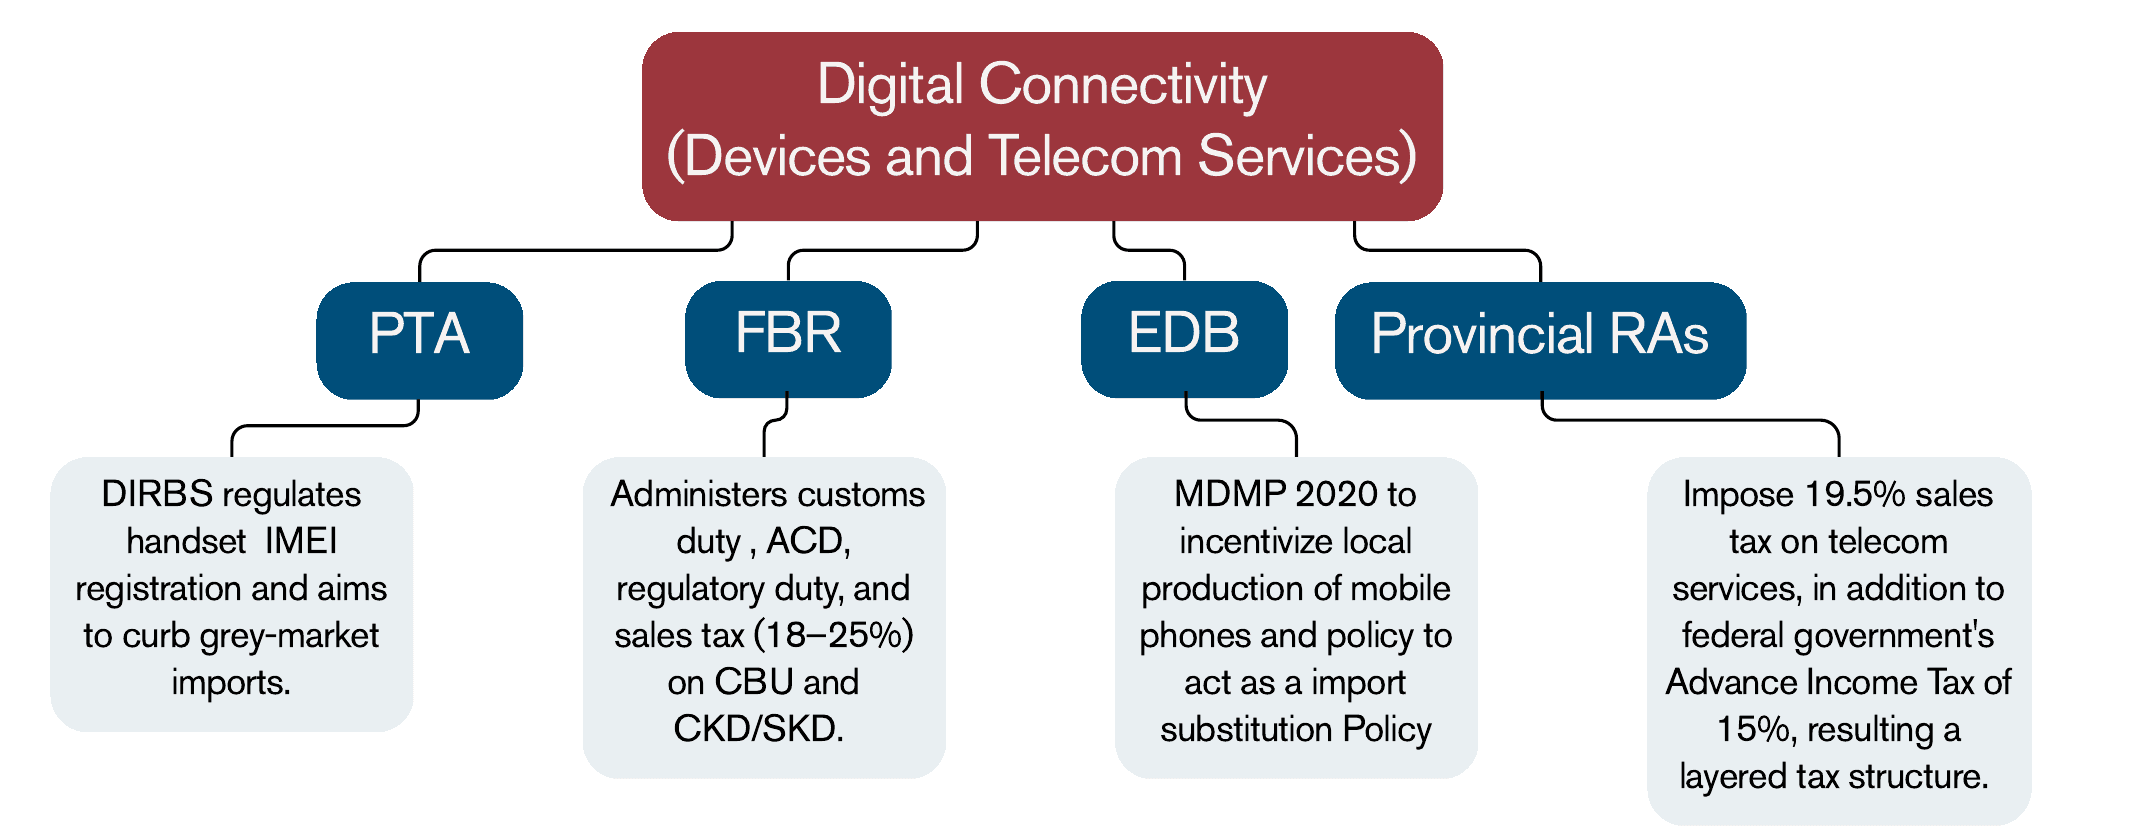
The regulatory ecosystem for digital connectivity is equally complex, with many players, including Pakistan Telecommunication Authority (PTA), Federal Board of Revenue (FBR), Engineering Development Board (EDB), provincial revenue authorities, State Bank of Pakistan (SBP), and Ministry of Information Technology, each playing different roles. However, the interaction of these players also results in a fragmented fiscal environment, where devices face heavy taxation, and telecom taxation is subject to both federal and provincial taxes. The detailed breakdown of activities of these ministries is listed in Figure 5.
Figure 5: Institutional and Regulatory Landscape for Digital Ecosystem in Pakistan
3. The Policy Environment
Device Identification, Registration, and Blocking System (DIRBS)
Device Identification, Registration and Blocking System (DIRBS) was introduced by the Pakistan Telecommunication Authority (PTA) in 2018 as a regulatory measure to curb the illegal imports and smuggling of mobile phones. Essentially, it was designed to address three interlinked policy concerns:
- Revenue leakages from informal handset imports
- Proliferation of counterfeit and non-standard (cloned, fake) devices
- Security risks associated with untraceable IMEIs
Anchored in Telecom Policy 2015 and operationalised through Mobile Device Identification, Registration and Blocking Regulations 2017, DIRBS enables PTA and mobile networks to identify and block non-compliant devices on national networks.
There are two ways to look at the DIRBS system: 1) Operational and 2) Fiscal. In operational terms, DIRBS acts as the enforcement front end, where every device is checked against the DIRBS database and categorized as “compliant”, “GSMA valid but not registered”, “non-compliant”, or “blocked”.
In fiscal terms, FBR has established a slab-based duty and tax structure for (CBU) mobile handsets that is directly embedded in the DIRBS regularization process. Through a series of SROs and General Orders, FBR has defined applicable tax and duty structures on the import of mobile handsets. These taxes and duties differ based on the cost of the mobile phone, the insurance and freight (C & F) value, and the customs regime. A detailed breakdown of taxes and import duties is given below.
| Sr. No. | C & F Value of Mobile Phone (US$) | Tax in CBU Condition (Rs.) – PCT 8517.1219 | Tax in CKD/SKD Condition (Rs.) – PCT 8517.1211 |
|---|---|---|---|
| 1 | Up to 30 except smartphones | 70 | 0 |
| 2 | Exceeding 30 and up to 100 | 100 | 0 |
| 3 | Exceeding 100 and up to 200 | 930 | 0 |
| 4 | Exceeding 200 and up to 350 | 970 | 0 |
| 5 | Exceeding 350 and up to 500 | 5000 | 3000 |
| 6 | Exceeding 500 | 11500 | 5200 |
Source: Finance Act 2025 and FBR
| HS / PCT Code | Product Type | Customs Duty (CD) | ACD | Regulatory / Fixed Duty (RD) Fixed duty (value-based) | Sales Tax (ST) | Total Tax Structure Applied |
|---|---|---|---|---|---|---|
| 8517.1390 | Smartphones – CBU | 0% | ≤ US$30 → Rs.300/set US$30–100 → Rs.3,000/set US$100–200 → Rs.7,500/set US$200–350 → Rs.11,000/set US$350–500 → Rs.15,000/set > US$500 → Rs.22,000/set |
18% ad valorem (≤ US$500) 25% ad valorem (> US$500) |
0% CD + Fixed RD + 18% / 25% ST | |
| 8517.1419 | Cellular Mobile Phones – CBU | 0% | Same fixed duty slabs as 8517.1390 | 18% ad valorem (≤ US$500) 25% ad valorem (> US$500) |
0% CD + Fixed RD + 18% / 25% ST | |
| Import of Kits of Locally Produced Phones | ||||||
| 8517.1310 | Smartphones – CKD / SKD | 0% | Nil | 18% ad valorem | 0% CD + 0 RD + 18% ST | |
| 8517.1411 | Cellular Mobile Phones – CKD / SKD | 0% | Nil | 18% ad valorem | 0% CD + 0 RD + 18% ST | |
Source: Finance Act 2025 and FBR
Impact of DIRBS on Consumers
DIRBS was initially designed to formalise the mobile phone market by curbing the influx of smuggled and counterfeit mobile phones. However, it was then used as a platform to tax connectivity. Impositions of various duties and taxes has significantly increased the prices of those mobile phones that are imported as CBU, in some cases (such as iPhones) making Pakistan one of the most expensive high-end mobile phone markets in South Asia. Pakistan’s imposed tax on mobile phones goes up to 35% for low-end Completely Built Units (CBUs) mobiles and is significantly higher than neighbouring countries (Amin & Gallegos, 2023).11 While CBU imports primarily affect middle to high end consumers, other taxes on mobile phones, particularly 18% sales tax on locally assembled devices constitute a major barrier to digital inclusion by increasing the cost of entry for middle income-households, students and gig-workers.
As noted earlier in the report, despite 81% of the population living in areas with 3G/4G connectivity, only 29% use the internet, creating a coverage gap of 52%. This gap is caused by high mobile and internet taxes, creating affordability problems for most of the population. Sector-specific levies on devices and services undermine the country’s broader development objectives.
Similarly, while local assembly has increased and illegal imports have been reduced after the introduction of DIRBS, recent trends indicate that a significant grey market for mobile phones still exists, particularly for high-end mobile phones, which are heavily taxed. This is done through IMEI cloning and the use of global or software-patched devices that temporarily evade DIRBS.12
Telecom Taxation Framework
Digital devices are not the only victims of high taxes, which can hinder digital connectivity. Rather, Pakistan’s telecommunication usage is also encumbered by one of the highest taxes in the region. This framework, which comprises multiple federal and provincial levies, directly inflates the cost of the internet, both in the form of mobile data and broadband, for consumers.
The taxation on telecom services in Pakistan is multi-layered, involving both federal and provincial governments. The cumulative burden on both service providers and consumers ultimately gets higher, as shown in the table below.
| Tax Component | Authority | Tax Rate |
|---|---|---|
| Advance Income Tax (AIT) | Federal Board of Revenue (FBR) | 15% |
| Federal Excise Duty (for Residents of Islamabad) | Federal Government | 19.5% |
| Provincial Sales Tax | Provincial Revenue Authorities | 19.5% |
Source: Finance Act 2025 and FBR
High taxes are imposed on both the supply and demand sides of the equation. On the supply side, the high tax burden reduces the capital available to Mobile Network Operators for infrastructure expansion and modernization. With around 42% of their total revenues directed to taxes and fees, profits for reinvestment remain minimal in Pakistan. This creates a vicious cycle where high taxes reduce the operator’s profitability, thus slowing the rollout of 4G/5G services and Fiber optic broadband. On the demand side, high taxes not only create a connectivity gap but also distort the economy.
Mobile Device Manufacturing Policy
In parallel to DIRBS, the Mobile Device Manufacturing Policy 2020 was introduced to promote the local mobile phone industry. To meet the rising demand for mobile phones in Pakistan, the policy was intended to increase the local manufacturing of mobile phones. The policy goals- and its outcomes- are mentioned in the following table.
The import structure of mobile phones in Pakistan has undergone a shift from CBU import to CKD/SKD import. Pakistan’s mobile phone manufacturing industry is still heavily reliant on imported CKD/SKD kits,13 remaining far below the ambitious targets set in MDMP 2020. This is further highlighted in the figures 6 and 7 on the following pages.
There has been limited progress toward genuine local manufacturing, only basic assembly operations have taken root. The policy has not resulted in meaningful localization of core components (e.g., power supplies/chargers, accessories), which continue to be imported.
This outcome is consistent with review of policy performance. Against an ambitious 49% localization target, actual localization in terms of manufacturing and value addition remains below 10%.14 Mobile parts being manufactured in Pakistan are low value components, including casings, outer body fitting, packaging materials and plastic accessories. Furthermore, the high end CBUs, including iPhones, Samsung and Google Pixels, are still being imported despite heavy taxes, thereby reducing overall consumer surplus.
Local mobile assembly plants in Pakistan have created over 60,000 jobs since 2021, driven by the government’s Mobile Device Manufacturing Policy (MDMP) and the Pakistan Telecommunication Authority’s (PTA) DIRBS system. Over 30 companies, including major brands like Samsung, Oppo, and Xiaomi, have established local units, attracting roughly $300 million in investment.
| Policy Goals | Targets | Achieved |
|---|---|---|
| Total localization target 49%, including 10% localization of Mother Board, 10% localization of Batteries, and 8% localization of Displays. | 49% total (incl. 10% Motherboard, 10% Battery, 8% Display) | Less than 10% localization |
| Creation of Direct and Indirect Jobs | 40,000 direct jobs and 300,000 indirect jobs | Not independently verified |
| Exports of the “Made in Pakistan” mobile Phones | No fixed targets | “120000 4G Smartphones” were exported to the UAE in 202215 |
Source: Finance Act 2025 and FBR
The import trend of mobile phones in Pakistan shows a clear shift rather than a reduction in aggregate foreign exchange outflows. As shown in the figure below, before the introduction of policy, from 2016-17 to 2018-19 the value of imports remained around $550 million. There was a sharp increase in imports of mobile phones after 2018. One thing is important to note here. The DIRBS was introduced in 2017, to prevent the illegal smuggling of mobile phones. Thus, the observed increase in imported phones can be attributed to DIRBS. This led to a shift from informal to formal import channels.
Despite this adjustment, the continued rise in imports after 2020 suggest that even after the introduction of MDMP 2020, there wasn’t a significant reduction in forex spending. This upward trajectory highlights that, contrary to policy’s goal of increasing localization and curbing import driven forex demand, total import value continued to expand significantly even after its implementation. While policy did facilitate a compositional shift from CBUs toward CKD/SKD, as reflected in detailed breakdown in subsequent figures 7 and 8, this did not translate into a decline in overall import expenditures and domestic production remained heavily dependent on imported components.
Figure 6: Trend of Mobile Phone imports in Pakistan (USD Millions)
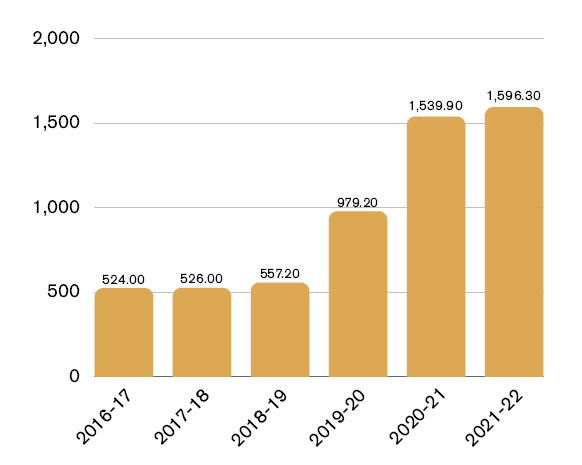
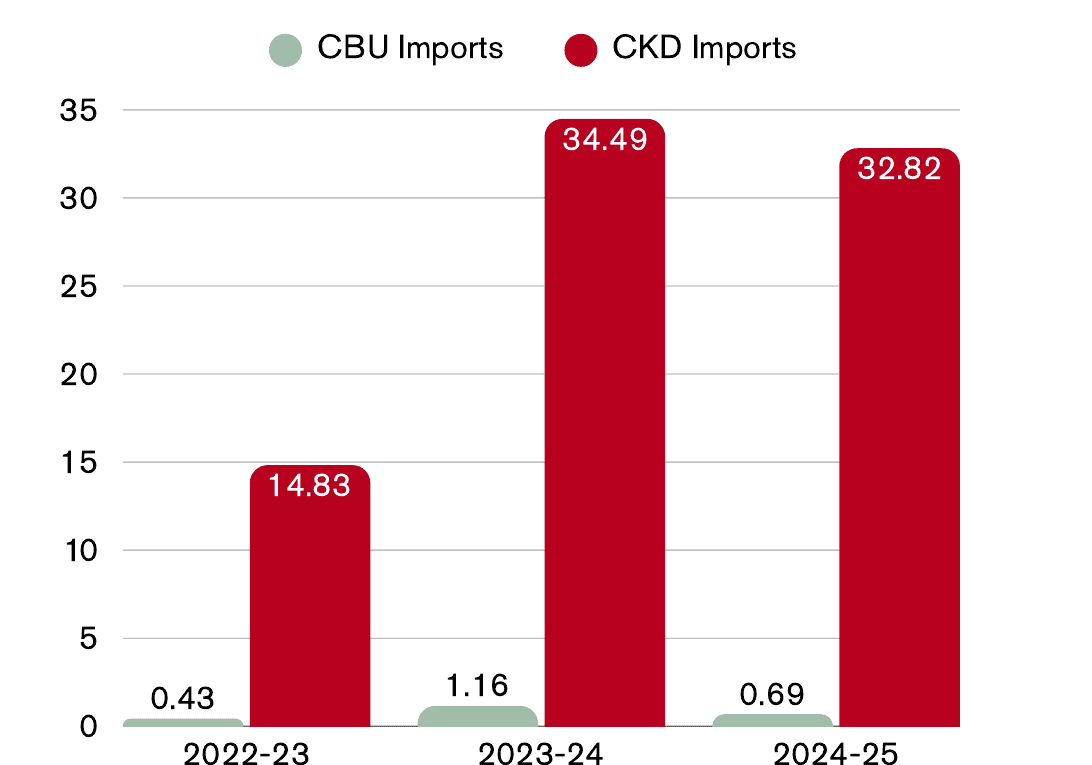
Quantity-wise, CKD imports are an order of magnitude larger than CBUs throughout the period after the policy was introduced in 2020, which is not surprising given tariff-based protections available to locally assembled mobile phones. Even at their peak, in 2023-24, as shown below, CBU imports remain below 1.2 million units, while CKD kits surge to over 34 million units in 2023–24, before moderating slightly but remaining structurally high.
Figure 7: CBU/CKD Imports Quantity (Millions)
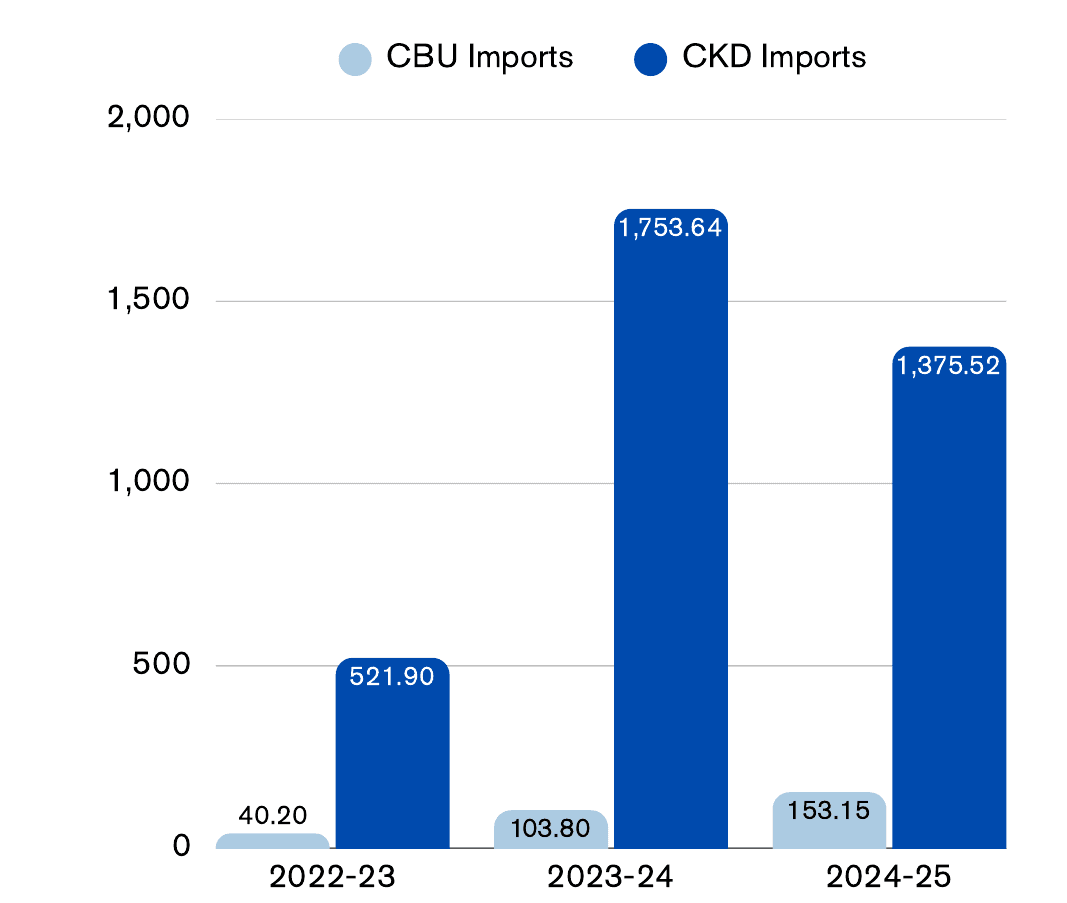
Value-wise, the pattern is even more revealing. CKD import values rise steeply from around US$ 500 million in 2022–2316 to nearly US$ 1.75 billion in 2023–24, followed by a modest decline. In contrast, CBU import values remain comparatively small. This implies that the foreign exchange burden previously associated with the import of mobile phones has not been reduced; it has merely been re-allocated to the imports of components instead of finished products. A comparison of figures 6 and 8 demonstrate this point.
Figure 8: CBU/CKD Import Value ($ Millions)
Source: Tradeverse (TIPP) Pakistan Single Window
The policy successfully discouraged CBUs through tariff-based measures and regulatory barriers but failed to induce domestic production of complex components. Retrospectively, such an expectation was also misplaced as countries need to develop an eco-system for manufacturing complex products which Pakistan does not have. Consequently, firms responded rationally by importing CKD/SKD kits and performing low-value assembly operations rather than value enhancing manufacturing.
Market Size and Growth of Mobile Phone Sales in Pakistan
Pakistan’s mobile phone market is substantial, with roughly 30–34 million handsets sold annually in recent years. According to PTA, approximately 30 million mobile phones were sold in FY 2024–25, which is a 12% decline from the 34 million sold in the previous fiscal year. This can be explained by a decline in general level of demand. On a calendar-year basis, 2024 saw a strong rebound in shipments, with roughly 33 million phones sold (compared to ~23 million in 2023), driven by a recovery in demand and a policy shift favouring local manufacturing. In fact, local production of devices jumped 47% in 2024 (to 31.38 million units) after a slump the year prior which was the result of import and dollar curbs. This included 18.64 million smartphones (59% of the total) and 12.74 million 2G feature phones, indicating that smartphone adoption is rising steadily. Pakistan’s market currently consumes around 1.4–1.5 million smartphones per month on average, highlighting a sizable and growing user base.
Literature on Merits and Demerits of Local Assembly
Many low- and middle-income countries have pursued import substitution policies, hoping that assembling phones locally will reduce consumer prices and build domestic industry. Governments often levy high tariffs on CBU phone imports while providing tax breaks on CKD kits. This creates a price gap intended to make locally assembled devices cheaper for consumers. For instance, Pakistan’s 2020 mobile manufacturing policy set a fixed tax differential (e.g., Rs 1,720 on $30–$100 phones), an 11–15% effective price difference favouring local CKD-assembled phones over imported CBUs. Similarly, Brazil’s “Lei do Bem” (2013)17 waived certain federal taxes on smartphones under R$1,500 if assembled locally, compelling firms like Samsung, Motorola, and even Apple’s partner Foxconn to produce in-country. Policymakers argue that local assembly can avoid import duties, lower freight costs, and tap cheap labour, thereby cutting retail prices. For example, a recent plan in Ethiopia claimed that “localized production could reduce retail prices by 15–20%”18 through import substitution, lower logistics costs, and targeted tax incentives. These anticipated savings are seen to make smartphones more affordable to millions of new users.
Despite these expectations, evidence from numerous countries shows only modest or no consumer price savings from local assembly once local costs are factored in. A 2025 GSMA analysis of African markets concluded that “local assembly has not translated into lower retail prices in most markets.”19 The reasons are structural. Even with assembly done domestically, key components (chipsets, displays, batteries, etc.) still must be imported, so import-related costs (shipping, customs/VAT on parts) remain significant. Moreover, local manufacturers face high energy costs, a limited pool of skilled labour (affecting productivity), and other overheads that erode the labour cost advantage. Critically, most local assembly operations lack economies of scale. Small-volume factories cannot match the efficiency of giant Asian contract manufacturers however in some products like chargers and accessories, aggregation in manufacturing can reduce the costs. According to the ITU/UN Broadband Commission, Transsion, a major phone maker, reported it can produce phones at a lower cost in its large China plant than in its assembly plant in Ethiopia. In short, many local factories have higher unit costs due to scale inefficiencies, which get passed on as higher prices or slim margins. Thus, while the MDMP aims to promote local industry and reduce import dependence, its reliance on tariff protection in a market lacking economies of scale risks creating a protected and inward-looking industry. This limits efficiency gains and constrains technological upgradation.
Key Factors and Findings behind Mobile Pricing in High Assembly
Across these examples, several key factors emerge that determine whether local assembly lowers consumer prices:
1. Tariff Differentials:
High tariffs on CBU imports are usually needed to make local assembly “cheaper” on paper. This can indeed create a price gap. However, if the tariff is too high, it may simply make all phones expensive, hurting consumers. Balanced policies (like India’s hypothetical 8% tariff scenario) can encourage local production with less consumer harm. Some studies argue that removing or reducing device taxes is the most direct way to reduce prices and boost adoption.
2. Local Production Costs:
Any savings on tariffs can be eroded by local costs. Labor in many low- and middle-income countries is cheap, but assembly labour is a small portion of the cost. Energy and utilities often cost more and outages can disrupt production. Moreover, new factories may have lower productivity initially. Capital and overhead per unit are higher when volume is low or when technology is imported. For example, GSMA reports that in Africa, these factors, combined with continued import of components, mean local assembly rarely undercuts import pricing.20
3. Economies of Scale:
This is perhaps the decisive factor. The scale of operations in China and Vietnam allows very low per-unit costs. Local assembly in a single developing country serves a smaller market. Even if labour is cheap, the lack of scale drives up unit costs. The Broadband Commission study found the value-added locally is quite marginal; India, despite assembling for a decade, still imports most high-value components and only adds value in low-tech steps (Broadband Commission, 2022).21 Without scale or local supply chains, unit costs remain higher than imported phones.
4. Quantitative Analysis of Total Cost of Mobile Ownership
This section develops a simple cost-based framework to estimate the total cost of mobile ownership for CBU imports in Pakistan. The methodology decomposes the price of mobile phone into its core components including fixed statutory charges such as Mobile Levy and Regulatory Duty, Withholding Tax, and sales tax applied on the adjusted tax base. By incorporating these tax elements into a single additive and multiplicative model, the framework allows for the estimation of both the total consumer price and the effective tax burden across different price slabs.
Total Cost of Imported Mobile Ownership:
TCOPKR = (PUSD × R) + L + RD + ST × (PUSD × R + L + RD) + WHT
Where TCOPKR = Total Cost of Ownership in PKR
PUSD = Price in USD
R = Exchange Rate
L = Mobile Levy (fixed-slab wise)
RD = Regulatory Duty (Fixed- Slab-wise)
ST = Sales Tax (18% on Mobile Phones valued up to $500, and 25% on phones valued above $500)
WHT = Advance Income Tax on imports.
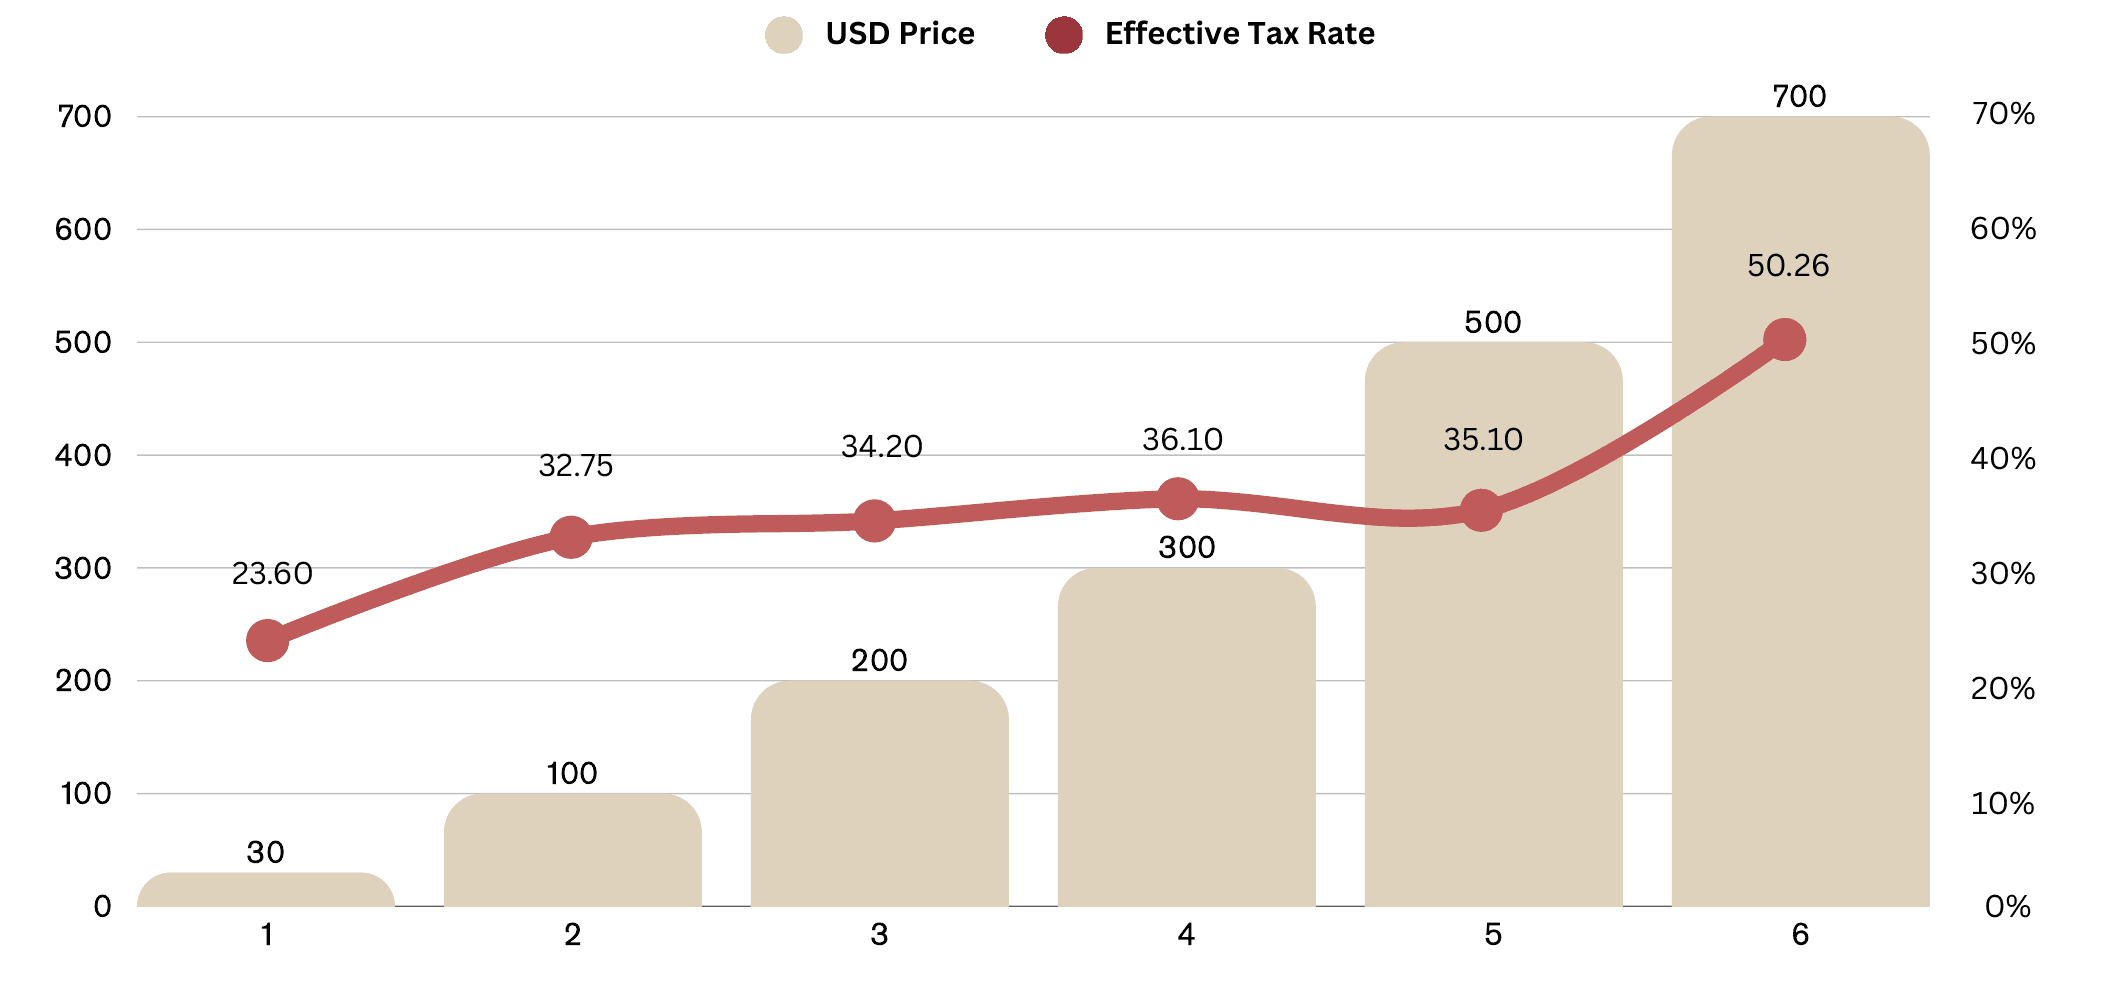
The taxation structure on mobile phone imports in Pakistan exhibits a disproportionate burden on mid- to high-range devices, with the effective tax rate (ETR) increasing as the base price of the device rises. For instance, a $100 device carries an ETR of around 33%, while a $700 device is taxed at over 50% of its base value. This indicates a steep escalation in tax liability that directly undermines affordability, particularly for high-quality smartphones, which are essential for accessing the internet and engaging in meaningful digital activities.
Notably, the tax system is not smoothly progressive; rather, it follows a slab-based structure with sharp jumps between brackets. A device priced at $500 is taxed at 18% sales tax, while a device just one dollar more expensive faces a 25% rate. This abrupt discontinuity distorts market behaviour and encourages invoice manipulation or underreporting. Such tax cliffs can lead to inefficiencies and market segmentation that are policy-induced rather than demand-driven.
| USD Price | PKR Value (1 USD = 280PKR) | Mobile Levy | Regulatory Duty | ST Rate | Sales Tax | WHT | Total Taxes | Total Cost | Effective Tax Rate |
|---|---|---|---|---|---|---|---|---|---|
| 30 | 8400 | 100 | 300 | 0.18 | 1512 | 70 | 1982 | 10382 | 23.6 |
| 100 | 28000 | 200 | 3000 | 0.18 | 5040 | 930 | 9170 | 37170 | 32.75 |
| 200 | 56000 | 600 | 7500 | 0.18 | 10080 | 970 | 19150 | 75150 | 34.2 |
| 350 | 98000 | 1800 | 11000 | 0.18 | 17640 | 5000 | 35440 | 133440 | 36.16 |
| 500 | 140000 | 4000 | 15000 | 0.18 | 25200 | 5000 | 49200 | 189200 | 35.14 |
| 700 | 196000 | 16900 | 22000 | 0.25 | 49000 | 11500 | 98500 | 294500 | 50.26 |
Source: Author’s calculations based on available tax rates on imported mobile phones
Figure 9: Effective Tax Burden on Mobile Phones across Price Ranges in Pakistan
Source: Author’s calculations based on available tax rates on imported mobile phones
5. The Tax Arbitrage Differential
The government has engineered a significant “arbitrage” in favour of local assemblers, making the locally produced mobile phones appear cheaper. Through the concessionary policies, local producers are being offered significant concessions in the form of zero customs duties, regulatory duties, and 18% uniform sales tax (unlike the CBUs, where sales tax is 18% for up to $500 mobile phones and 25% for mobile phones valued above $500). While the taxes imposed by FBR and the Mobile Device Manufacturing Policy acted together in a way to promote the “Made in Pakistan” mobile phones, the resulting assembly, instead of manufacturing of mobile phones, has not resulted in meaningful cost savings for the consumers. While both locally assembled and CBU mobile phones are exposed to global price and exchange rate fluctuations, high import dependence in local assembly constrains domestic value addition, limiting the sector’s ability to reduce cost volatility. High energy costs, inefficiencies in local production, and a lack of scale further erode any cost advantage from cheaper labour.
Case Study — Bangladesh
Bangladesh initially imposed a 25% duty on imported smartphones while favouring local assembly with lower taxes, hoping to develop a domestic industry. By the mid-2020s, however, smartphone prices in Bangladesh were among the highest in the region, and a thriving grey market persisted. In 2026, the government reversed course, slashing import duty from 25% to 10%. The National Board of Revenue estimated that this would cut the retail price of high-end imported phones by Tk 5,500 (≈$50+) on average. Locally assembled phones would also get slightly cheaper, but only by about Tk 1,500 (~$15), since their components’ duty was only modestly reduced (from 10% to 5%). This stark difference revealed that, under the previous policy, local assembly had only a small price advantage – end-users were still paying nearly the same, because local assembly costs and taxes on parts offset much of the savings.
Case Study — Kenya
Kenya’s experience with local smartphone assembly demonstrates the similar example of local assembly without meaningful consumer surplus. Despite policy incentives, tax breaks, and the launch of the country’s first smartphone assembly plant (EADAK), locally assembled phones ended up retailing for KSh 7,500–10,000 (approximately $55–$75) well above the promised KSh 5,000 (~$40) affordability target. This price gap was driven by continued dependence on imported components (still paid for in USD), high energy and labor costs, limited economies of scale, and tax design flaws. Ultimately, the modest tax arbitrage intended to benefit consumers was largely absorbed by assembler operating costs. Similar patterns are observed in other countries like Brazil, Nigeria, and Egypt, where local assembly rarely translates into lower prices unless accompanied by real manufacturing capability and supply chain localization. Kenya’s case thus reinforces the argument that promoting assembly without industrial deepening may shift the location of production but not reduce the burden on consumers.
6. The Grey Market & Distortions Module
Excessively high taxes on any sector are proven to be counterproductive, fuelling the very “illegal imports” DIRBS was meant to curb. High import duties and taxes on mobile phones in Pakistan, with effective tax rates exceeding 50% on premium devices, have led to several unintended outcomes including a surge in grey-market activity for high end mobile phones. Similarly, such steep mark-ups have made premium devices unaffordable through legal means, prompting people to turn to grey-market solutions. Faced with these costs, many consumers and traders turn to the grey market. This involves importing or buying phones that bypass the official customs and PTA registration system. These smuggled devices often undergo software “patching” or IMEI cloning to evade the PTA’s Device Identification, Registration, and Blocking System (DIRBS). By altering the phone’s unique identifier to a duplicate or invalid IMEI, smugglers can activate non-tax-paid phones on local networks, thereby bypassing the official registration and duty payments. Industry officials note that high-end phones (e.g., models costing Rs80,000 and above) are routinely sold in this grey market22 after being patched to fool DIRBS.
The scale of this illicit trade is substantial. PTA blocked approximately 100 million illegal mobile devices detected on networks in FY 2024-25, which have been possibly accumulated in the market over some years.23 This included nearly 72 million counterfeit or replica phones and 27 million devices with cloned/duplicate IMEIs, a clear indication of mass IMEI tampering to skirt taxes. While these figures reflect cumulative detections rather than the simultaneous stock of active illegal phones, they nonetheless suggest persistent attempts at IMEI tampering and the circulation of non-compliant devices. Enforcement agencies have only limited success curbing the supply, whereas sellers brazenly advertise “non-PTA-approved” phones online, and many users now carry two phones, one officially registered and another unregistered, to save on duties.
7. Digital Affordability: Insights from HIES 2024–25
To further understand the state of digital access and affordability challenges in Pakistan, this section draws on micro-level insights from the Household Integrated Economic Survey (HIES). Unlike national averages, such as GNI per capita, HIES provides disaggregated household-level data that allows for a more in-depth assessment of mobile ownership and usage patterns, as well as regional disparities.
In Low- and Middle-Income Countries (LMCIs), the poorest quintiles spend a greater portion of their income on devices. On average, entry-level phones cost about 16% of the monthly income, but this spikes to 44% for the poorest 40% and 55% for the poorest 20%.24
Several international benchmarks have been established to gauge the affordability of digital access. The UN Broadband Commission recommended that 1 GB broadband data should cost less than 2% of monthly GNI per capita. While this rule applies to the internet service pricing, devices lack a formally universal target. However, recent analyses suggest a de facto benchmark of around 20% of monthly income for an entry-level smartphone. Globally, the median cost of a basic internet-enabled handset is about 19-20% of monthly GDP per capita. For South Asia specifically, the figure is roughly 23% of monthly income.25 Thus, these ratios serve as a yardstick.
Pakistan’s current affordability gap becomes evident against these benchmarks. According to A4AI, Pakistan has made strong progress on data costs, where 1 GB of mobile data here is just 0.5% of average income, comfortably meeting the UN’s 2% affordability target. Even a 5GB monthly plan is 1.5% of income on average,26 indicating that internet service in Pakistan is relatively affordable by global standards. However, the stark contrast is in device affordability. A4AI finds that a smartphone costs about 53% of the average monthly income in Pakistan. This 53% figure far exceeds global and regional affordability range and highlights a severe affordability barrier. This affordability barrier stems from the upfront price of devices, thus acting as a big barrier to digital access in many countries.
Incorporating HIES-based Evidence on Device Affordability in Pakistan
The broader global standards and patterns are further substantiated by direct analysis of Pakistan’s latest HIES 2024-25 data. Using the weighted household expenditure data, we calculated an affordability ratio to determine how much of a household’s monthly expenditure would be consumed by purchasing a PKR 25000 entry-level smartphone.
Device Affordability Ratio = Device Price / Monthly Household Expenditure (by population – weighted per capita quintiles)
The affordability ratio calculations are based on entry level smartphone of PKR 25,000. This value reflects the lowest-cost model phones offered by the three most-sold brands in Pakistan, according to PTA data. These three most sold phones are Infinix (Smart 10), VGO TEL, and Vivo (Y02T), with a price range from PKR 22,000-25,000. These models represent the baseline cost for mobile connectivity access in the local market.
The national mean affordability ratio stands at 31%, implying that for an average Pakistani household, over 30% of monthly spending would be needed to acquire a basic smartphone. Obviously, households do not make these spending decisions on a daily basis, however these benchmarks provide a comparative insight.
Importantly, the burden of this cost is not distributed equally across income levels. A breakdown by consumption quintiles shows stark disparities.
| Quintile | Device Affordability Ratio | Monthly Expenditure in PKR (HIES 2024-25) |
|---|---|---|
| 1 | 0.62 | 40,148 |
| 2 | 0.48 | 52,283 |
| 3 | 0.40 | 62,026 |
| 4 | 0.33 | 75,811 |
| 5 | 0.19 | 1,34,447 |
| Overall Mean | 0.31 | 78,523 |
Source: HIES 2024-25
The above table suggests that for the lowest 20% of households, the cost of an entry-level smartphone constitutes approximately 62% of monthly per capita expenditure, effectively requiring more than half of their monthly resources to acquire a basic device. Even for the second and third quintiles, affordability ratios remain critically high at 48% and 40%, respectively, levels that are far beyond any reasonable threshold for essential goods.27 The national average affordability ratio of 31.8% underscores that even entry-level mobile phone ownership is not broadly accessible without significant financial trade-offs.
The empirical findings from the HIES data reinforce the global literature’s argument that device affordability is a major barrier to digital inclusion. The findings clearly indicate that mobile devices are priced as quasi-luxury goods in Pakistan. This disproportionately excludes lower-income populations from digital participation, reinforcing existing inequalities in access to education, employment, financial services, and online markets.
Impact of Limited Mobile Affordability on Digital Participation in Pakistan
As discussed earlier in the report, Pakistan’s digital divide presents a worrisome picture. With around 52% of the internet usage gap and uneven access across the gender and income lines, Pakistan represents a country with immense potential, yet that potential is being untapped or hindered due to the affordability issue. Millions of Pakistani women remain “digitally invisible” because they are less likely to own a mobile phone compared to men in Pakistan (Refer to Section 2).
The affordability barrier, coupled with a lack of digital literacy, directly hampers education and skill development in Pakistan. Digital literacy and online access are increasingly essential for modern education. Students who cannot get online are deprived of vast learning resources, from online courses and libraries to educational videos. This particularly hurts rural girls, who often have limited access to quality schools and could benefit from distance learning if they had the means. Without affordable devices and internet, these girls miss out on both academic content and the chance to build digital skills for the future. Stakeholders note that digital education, if scaled equitably, could help reach remote regions where “school infrastructure and female teachers have been historically lacking,”28 potentially serving as a substitute for formal schooling for marginalized girls. In sum, the affordability barrier to technology directly translates into an education barrier, with the poorest students, especially girls, falling further behind in the knowledge economy.
Effects on Freelance and Gig Economy
Pakistan’s fast-growing freelance and gig economy offers new avenues of employment, but only for those who can get online. Pakistan has now over 1.5 million freelancers, working for clients worldwide and contributing to the country’s broader IT and IT-enabled services exports. These IT and IT-enabled services exports totaled approximately $3.2 billion in 23-24,29 highlighting a potential for this sector to grow. For a country that has stagnant growth of exports, hovering around $30-35 billion and concentrated in a few sectors, the IT sector and freelancers are a way forward, requiring little physical capital and employing more skilled labour. Importantly, freelancing also opens doors for women who cannot participate in the traditional workforce due to social and mobility constraints. In a country where labour force participation of women remains under 25%, online work is a promising equalizer, provided women have the necessary digital access.
There are a few examples where affordable access and training have coincided; women’s participation in the gig economy has shown success. Initiatives in tech training for women demonstrate that when young women are given exposure to computers and the internet, they rapidly acquire marketable skills and secure online jobs. Such initiatives include PTCL’s Ba-Ikhtiar Programme, which has a completion rate of around 79%.30 In this program, women used smartphones to access global markets and even launched an AI-powered online fashion show to showcase their products.
Studies show that, on average, a Pakistani woman who owns a mobile phone has a 36% higher probability of being in the labour force compared to those who don’t own a mobile phone (Amber & Chichaibelu, 2023).31 This suggests how access to even a basic internet device can be a gateway to income.
In addition to the freelance economy, the gig economy has been contributing meaningfully to the economy of Pakistan. An independent study suggests that FoodPanda contributed $1.2 billion to the economy in 2023-24,32 creating a strong multiplier effect across different sectors such as food, hospitality, manufacturing, transport, and retail. Similarly, ride-hailing apps, such as Indrive, Yango, and Bykea have also significantly impacted Pakistan’s economy by disrupting traditional transport sectors, offering competitive mobility options, and providing livelihood opportunities to many. Given that these services also rely on affordable devices and the internet, the cost of mobile devices and internet access significantly affects these service providers.
The evidence is thus clear that affordable access to mobile devices and the internet is directly linked to economic opportunities in education, commerce, and work. As a result, policymakers widely advocate measures to narrow the digital divide, which creates barriers to inclusion. The stakeholders including telecom operators, ecommerce firms and IT exporters have advocated for tax reforms in the digital sector. Both industry groups and development organizations urge eliminating or reducing the heavy taxes on devices and data to make connectivity affordable for marginalized groups. GSMA has also highlighted the need to gradually eliminate the 15% advance income tax and 19.5% sales tax on mobile services,33 which reportedly creates additional barriers to digital inclusion for low-income households.
In conclusion, the limited affordability and access to mobile devices in Pakistan are a linchpin issue connecting to education outcomes, e-commerce growth, freelance employment, and gender inequality. The data and cases from Pakistan underscore a clear narrative that improving device affordability and expanding internet access will directly unlock economic opportunities. By closing the digital divide, Pakistan stands to gain not only enhanced GDP and innovation but also a more inclusive workforce and educated society. Conversely, failing to address affordability will leave critical human potential untapped. Thus, bridging the gap and making smartphones and connectivity accessible to all is a development imperative for Pakistan’s future.
8. Policy Recommendations
1. Harmonized 18% Sales Tax on Devices
Rationale:
Currently, mobile phones imported into Pakistan face a tiered sales tax regime: 18% on devices valued up to $500, and a punitive 25% on devices exceeding $500. While the policy intends to discourage luxury imports and protect local assemblers, its consequences have been counterproductive, including grey market expansion resulting in revenue leakage and consumer penalty.
Policy Recommendation:
In the Eighth Schedule of the Sales Tax, 1990 the differential rate of sales tax on imported mobiles, depending on the value, should be omitted. Harmonized 18% sales tax should be applicable on imports of CBU devices, irrespective of their value.
Expected Outcomes:
- Encourages formal market participation by lowering the incentive to engage with grey or illicit sources.
- Broadens the tax base without penalizing digital access, especially for users who rely on high-end smartphones for work, education, or freelancing, ultimately increasing compliance and government revenue.
2. Reduced Advance Income Tax (AIT) and Rationalized Service Tax
Rationale:
While the internet cost falls under the affordability threshold for individuals in Pakistan, the 15% AIT on mobile services is regressive, disproportionately burdening low-income users who typically do not file taxes to claim refunds. Additionally, the 19.5% service tax on internet usage further limits digital inclusion. A reduction to 8% AIT and 18% GST on services would increase affordability for all users, particularly marginalized groups.
Policy Recommendation:
- Lower AIT from 15% to 8% on mobile services and data usage.
- Harmonize GST on telecom services to 18 % nationally (eliminate provincial disparities).
Expected Outcome:
- Higher affordability for data packages, with direct benefits for students, freelancers, and low-income users.
- Reduction in tax-induced digital exclusion for women and rural populations.
- Increased data consumption and broadband penetration, expanding the digital economy.
3. MDMP Tariff Rationalization and CKD/SKD Transition
Rationale:
Unconditional tax concessions to local assemblers have created rent-seeking behaviour without corresponding benefits to the economy. To shift from low-value assembly to true industrial capability, the government must implement a performance-based incentive framework, tied to measurable outcomes.
Policy Recommendations:
Learning from India and Vietnam, Pakistan’s tariff rationalization must go beyond favouring CKD/SKD imports. Instead, it should:
- Introduce gradual duty restructuring where CKD/SKD imports that do not meet a minimum localization threshold attract higher tariffs.
- Tax incentives and fiscal support must require formal partnerships with global OEMs that include 1) Establishment of local R&D labs, 2) Deployment of technical experts for knowledge sharing, and 3) Licensing arrangements that gradually localize key modules.
- Introduce a Value-Added Manufacturing Index (VAMI) for plant-level performance audits.
- Any firm benefiting from protectionist policies must demonstrate a clear export performance trajectory and job creation targets.
True industrial deepening requires not just protection, but structured accountability and incentivization. Without this, the current CKD/SKD-driven regime risks perpetuating import dependence and missing the productivity gains of real manufacturing. True localization will emerge when there is an economy of scale, market access, logistics readiness, and technology transfer.
Expected Outcomes:
Implementing these reforms as a comprehensive package can yield the following:
- Affordability Gains: Lowering ETRs and taxes on services would directly improve per capita device affordability, currently averaging 61.5% of monthly per capita expenditure across income quintiles (based on HIES analysis).
- Digital Equity: By reducing entry barriers, these reforms would empower more women, students, and rural users to enter the digital economy.
- Revenue Efficiency: Flattening tax rates and removing abrupt duty cliffs could reduce grey market leakages and boost actual tax collections over time.
- Industrial Upscaling: Properly sequenced CKD-to-manufacturing transitions would deepen local capabilities and shift from mere assembly to high-value production.
9. Conclusion: A Case for Market-Driven Digital Access
The government must stop treating digital devices as luxury goods. In today’s digital economy, smartphones- and tablets- are a basic infrastructure, critical for learning, livelihoods, financial access, and civic participation. Yet, high and uneven taxation has made mobile ownership prohibitively expensive, especially for low-income households, reducing consumer welfare and locking millions out of meaningful digital participation.
While the Mobile Device Manufacturing Policy aimed to promote self-reliance, it has delivered assembly with minimum value addition. Pakistan lacks the pool of cheap skilled labour and technology transfer arrangements needed to build competitive, high-spec devices. Until such capabilities are developed, locally assembled phones cannot meet global performance standards, especially in the new era of 5G, and consumers are left with overpriced, underpowered devices.
Moreover, protectionist tariffs have created an artificial price gap, forcing users to either downgrade quality or resort to grey markets. This restricts choice, reduces product diversity, and undermines consumer surplus, the very metric of welfare that efficient markets aim to enhance.
The way forward is phasing out distortive taxes, aligning industrial support with exportable value addition, and letting market competition, not fiscal engineering, drive affordability, innovation, and digital inclusion. Until then, the current policy regime will continue to limit both access and aspiration in Pakistan’s digital journey.
Notes
- Authors are grateful to Atlas Network, for supporting this research and publication. They also acknowledge Mr. Parvez Iftikhar for review and comments.
- UNCTAD (2019), Digital Economy Report 2019, https://unctad.org/publication/digital-economy-report-2019
- GSMA (2025), The Mobile Economy 2025, https://www.gsma.com/solutions-and-impact/connectivity-for-good/mobile-economy/
- Ibid
- https://www.na.gov.pk/uploads/documents/679b239e8d57f_451.pdf
- GSMA (2025), Unlocking Pakistan’s Digital Potential: Reform, Trust and Opportunity https://www.gsma.com/about-us/regions/asia-pacific/gsma_resources/pakistans-digital-2025
- GSMA. (2024). Realising Pakistan’s aspiration to become a digital nation, https://www.gsma.com/about-us/regions/asia-pacific/gsma_resources/digital-nation-pakistan/
- Dawn July 19, 2025 https://www.dawn.com/news/1925145
- Khan (2026), Pakistan IT exports surge nearly 20% to $2.61bn in July–January, Pakistan IT exports surge nearly 20% to $2.61bn in July–January – Technology – Business Recorder
- GSMA, The Mobile Gender Report (2025)
- Rami Amin; Gallegos, Doyle. Affordable Devices for All Innovative Financing Solutions and Policy Options to Bridge Global Digital Divides (English). Washington, D.C. : World Bank Group. http://documents.worldbank.org/curated/en/099080723143031193
- https://profit.pakistantoday.com.pk/2026/04/27/mobile-manufacturers-warn-of-imei-cloning-oppose-used-phone-imports/
- PCRA 2026, Mobile Phone & Allied Products
- This was stated in an interview by a senior government official. Identity has been withheld.
- https://www.pta.gov.pk/category/pakistan-exports-120000-locally-manufactured-mobile-phones-1178732511-2023-06-01
- Note that volume of both CKDs and CBUs is significantly lower in 2022-23 because of import restrictions and Letter of Credit (LCs) control countrywide to maintain forex reserves in Pakistan.
- Mobile Ecosystem Forum (2015), Brazil Focus: The Smartphone Market, https://mobileecosystemforum.com/2015/09/30/brazil-focus-the-smartphone-market
- FurtherAfrica (2025), Ethio Telecom and TINNO to Advance Smartphone Assembly in Ethiopia, https://furtherafrica.com/2025/10/15/ethio-telecom-and-tinno-to-advance-smartphone-assembly-in-ethiopia
- TechAfrica News (2025), Tax Reforms vs Local Assembly: Which Path Truly Leads to Africa’s $30 Smartphone? https://techafricanews.com/2025/11/27/tax-reforms-vs-local-assembly-which-path-truly-leads-to-africas-30-smartphone
- TechAfrica News (2025)
- State of Broadband Report 2022: Geneva: International Telecommunication Union and United Nations Educational, Scientific and Cultural Organization, 2022. License: CC BY-NC-SA 3.0 IGO. Available at: https://www.broadbandcommission.org/publication/state-of-broadband-2022/
- The News International. (2024, May 13). Smuggled, non-PTA-approved cell phones swamp Pakistan’s markets, online platforms: Industry. https://www.thenews.com.pk/print/1187217-smuggled-non-pta-approved-cell-phones-swamp-pakistan-s-markets-online-platforms-industry
- Profit Pakistan Today. (2026, January 7). PTA blocks 100 million mobile devices in fiscal year 2024–25 to curb illegal usage. https://profit.pakistantoday.com.pk/2026/01/07/pta-blocks-100-million-mobile-devices-in-fiscal-year-2024-25-to-curb-illegal-usage
- GSMA (2024), GSMA Handset Affordability Coalition. https://www.gsma.com/solutions-and-impact/connectivity-for-good/external-affairs/home/gsma-handset-affordability-coalition/
- GSMA (2023), Making internet-enabled handsets more affordable. The News International. (2024, May 13). Smuggled, non-PTA-approved cell phones swamp Pakistan’s markets, online platforms: Industry. https://www.thenews.com.pk/print/1187217-smuggled-non-pta-approved-cell-phones-swamp-pakistan-s-markets-online-platforms-industry
- A4AI (2024) Pakistan digital connectivity brief. https://adi.a4ai.org/wp-content/uploads/2021/08/Pakistan-Brief.pdf
- A key limitation of this analysis arises from the nature of the Household Integrated Economic Survey (HIES) itself. While HIES is nationally representative, it is well understood that high-income and elite households are systematically underrepresented in household surveys due to non-response, underreporting, and sampling constraints. As a result, the upper tail of the income distribution is effectively truncated, which is reflected in the relatively modest average expenditure of the richest quintile (around PKR 134,000).
- NORRAG Global Education Center (2021) The Educational Gender Gap under the Covid-19 Pandemic and Emerging Solutions. https://www.norrageducation.org/the-educational-gender-gap-under-the-covid-19-pandemic-and-emerging-solutions-by-wajeeha-hazoor-bajwa
- https://tribune.com.pk/story/2492783/freelancing-providing-digital-lifeline-for-pakistans-economy
- World Economic Forum (2025). https://www.weforum.org/stories/2025/05/ai-fashion-show-highlights-how-digital-access-is-empowering-women-in-pakistan
- Amber, H., & Chichaibelu, B. B. (2023). Narrowing the gender digital divide in Pakistan: Mobile phone ownership and female labor force participation. Review of Development Economics, 27(3), 1354–1382. https://doi.org/10.1111/rode.12994
- Business Recorder (2025) FoodPanda added $1.2bn to economic activity in FY24. https://www.brecorder.com/news/40376737
- GSMA 2024, Realising Pakistan’s Aspiration to become a Digital Nation. https://www.gsma.com/about-us/regions/asia-pacific/wp-content/uploads/2024/08/DNS-Islamabad-report-Final.pdf